Employer contributions, statutory benefits, additional payments, accrued entitlements and potential exit costs all need to find their way into the budget. Some are regular payroll costs, others build over time or become payable at specific points during the employment relationship.
Research from the Inter-American Development Bank found that across 19 Latin American and Caribbean countries, the average non-wage cost of formal salaried employment reached 51.1% of formal wages. Labour costs have also increased over time, with the gap between markets growing.
Now, there is no suggestion that 51.1% should simply be added to every LATAM salary; this figure is merely an average, and individual markets work very differently across the region. For a business considering a hire, the useful calculation starts with salary, but needs to show everything that comes after it.
What sits on top of Salary?
A simple annual hiring calculation might start with: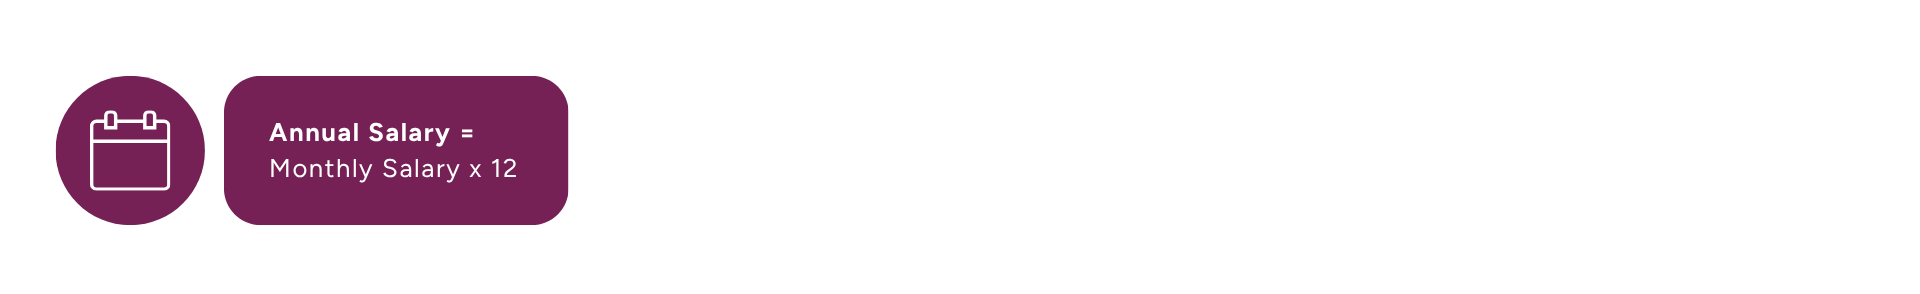
A more complete employment budget may need to account for: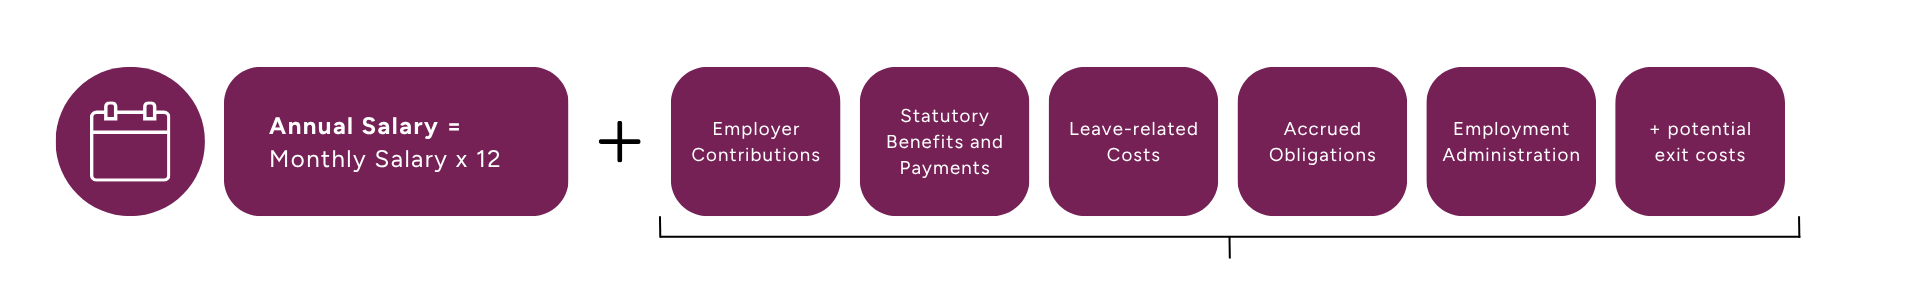
The purpose of this calculation isn’t to add every possible cost to every hire. It’s to identify which obligations apply to the intended employment arrangement and account for them before comparing markets or approving the budget.
Employer Payroll Contributions
Gross salary is only part of what an employee costs the business. Employer contributions and other payroll obligations sit alongside it, and these can materially change the economics of a hire. This becomes particularly important when comparing markets. Two roles with the same salary on paper can look quite different once the local cost of employing that person is factored in.
Statutory Benefits and Additional Payments
Employers also need to account for mandatory benefits and payments outside of ordinary monthly salary. Additional salary payments such as Brazil’s 13th salary, Colombia’s prima de servicios and Mexico’s aguinaldo are examples of how statutory payments can have different calculations and payment schedules.
Other entitlements and obligations may also affect the overall hiring budget, making it important to understand the complete employment package rather than focusing on one highly visible statutory requirement.
For more detail on these specific payments, read our guide to 13th and 14th month salary.
When you pay matters as much as what you pay
Some costs appear in payroll every month. Others build in the background and only become payable later in the year, or when something changes in the employment relationship.
This therefore creates an important distinction between annual employment cost and cash flow. When building a realistic hiring budget you should therefore look to answer two questions:
- What will this person cost over the full year?
- When will those costs actually need to be paid?
This becomes particularly relevant when building a team rather than making an individual hire.
Accured Obligations can be easy to overlook
Some costs don’t show up in payroll straight away. They build over time, creating commitments that the business will need to meet later. Looking only at what’s being paid each month can therefore give an incomplete picture of what the team is really costing. As the team grows, so do those accumulated commitments. Factoring them into the budget from the outset gives a much clearer view of the longer-term cost of the workforce.
Exit costs begin before employment ends
The cost associated with ending employment is another area that can be overlooked when the original business case focuses primarily on salary and monthly payroll.
Depending on the circumstances, a final employment settlement could include:
- Outstanding salary
- Accrued statutory payments
- Unused entitlements
- Notice-related payments
- Statutory severance or indemnification
- Other applicable termination-related amounts
Total exposure can be influenced by factors such as length of service, contractual terms and the circumstances in which employment ends; when hiring supports a fixed project, market trial or uncertain growth plan, this is particularly relevant.
The hiring route changes the cost calculation
When employing through your own local entity, salary and employment-related costs may sit across payroll, HR, finance and other internal budgets. For organisations with an established presence and long-term hiring plans in a market, that may be entirely appropriate.
An Employer of Record (EOR) offers a different route. The EOR becomes the local employer, allowing the business to employ people without first establishing its own local entity, while the business continues to manage their day-to-day work.
This can be particularly useful when entering a new market, making an initial hire or testing an opportunity before committing to a permanent local structure. Instead of establishing the employment infrastructure itself, the business can use an existing local employment framework.
From a cost perspective, this can also make the employment commitment easier to see. Salary, employer contributions, statutory entitlements, employment administration and the EOR’s service fee may be brought together within the overall employment-cost calculation.
That doesn’t automatically make EOR the cheapest route, nor does it mean it will be the right option for every expansion. The value is in giving businesses a practical route to employ in a market before the scale or certainty exists to justify establishing their own entity. A local entity may become more appropriate as the team and long-term commitment grow.
Contractor arrangements, on the other hand, require a different assessment. Here the headline contractor fee may appear simpler to budget for, but the organisation still needs to establish that the proposed arrangement is appropriate for the working relationship.
Look beyond the annual total when comparing LATAM hiring options
When comparing markets or hiring routes, the lowest headline figure does not necessarily tell you which option offers the best fit. What matters is understanding what is driving the final total. To uncover this, you should create a cost comparison by separating:
- Gross salary
- Employer contributions and payroll costs
- Mandatory benefits and statutory payments
- Leave and accrued entitlements
- Timing of major payments
- Potential termination exposure
- Employment administration costs
- Provider fees, where applicable
Breaking the figure down this way makes it easier to see whether an apparent cost difference is driven by salary levels, additional employment obligations, the hiring route or simply how the quotation has been structured.
What to ask for before approving a LATAM hiring budget
Before approving a hire, ask for an employment-cost model built around the location and proposed hiring arrangement. This will enable you to understand the following:
- What sits above gross salary
- Which costs recur and which accrue
- When significant payments become due
- What potential exposure has been considered
- Which assumptions underpin the calculation
- What represents employment cost vs provider fees
You should not be looking to identify the cheapest place to hire, but to gain a complete understanding of the financial commitment behind each option before making that final call.
Planning a Hire in Latin America
Whether you've selected a market or are still comparing options, Workwell Global can help you understand the likely annual employment cost and practical hiring routes available to you.
Explore Our Latest Resources

Workwell Global Further Expands Footprint and Capability with Launch into Latin America
Workwell Global expands its in-house international capability with new teams and infrastructure in Brazil and Colombia.
Explore What’s Next In Latin America
Whether you have an active opportunity in LATAM or simply want to understand the region better. Sign up today!

Hiring In Brazil: What You Need To Know
Learn how Workwell Global can help you compliantly place and payroll contractors when hiring across Brazil.